SYSTEMIC DIAGNOSTICS // FIDUCIARY ARCHIVE
THE FIDUCIARY REGISTRY
Independent, non-smoothable intelligence logs and systemic diagnostics compiled over more than a decade of tracing transaction metadata. This archive operates as a sovereign database built to strip away narrative seduction, exposing where portfolio assets are weaponised as pawns within private equity's opaque black box. It equips Level 1 allocators with the precise metrics required to enforce baseline accountability and cleanly separate authentic operational execution from debt-engineered luck.
The Anatomy of a Zombie Asset: Seeing the LPs’ €500 Billion Fiduciary Void
How do we close Private Equity’s €500 billion fiduciary void? This clinical briefing interrogates the "Golden Goose" Ghost Economy Deficit to demonstrate why Limited Partners must transition from passive dependency to Sovereign Agency through independent diagnostic telemetry.
Throughout my life, people have observed: “We don’t understand you. You just seem to sit there thinking.” In a world that confuses “action” with “solving problems”, deep thought is often mistaken for inaction.
But for a diagnostician, thinking is the action.
Last week, a post by Professor Claudia Zeisberger exposed a €500 billion void that three decades of Private Equity industry guidelines have failed to close. Sitting with this data, I wrote “The Golden Goose and the Food Diary” to structure my thinking—synthesising the work of the industry’s most rigorous independent thinkers: Ludovic Phalippou, Claudia Zeisberger, Alexandra Heal, and Baraa Shaheen. It is my clinical look at why Private Equity governance is failing. When it clearly shouldn’t.

While the €500 billion fiduciary void defines the industry-wide emergency, the €513.8 million Ghost Economy Deficit in the Golden Goose case study provides the clinical invariant proof of how that void manifests in a single sponsor-to-sponsor Secondary Buyout (SBO) transaction.
The answer isn’t about LPs “begging” for more granular reporting within the existing ILPA Transparency Pillar—it is the transition from Institutional Dependency to Sovereign Agency. While ILPA provides the necessary legal lamppost, it remains a request-response model that leaves the GP as the sole author of the narrative.
It is about the moral refusal to bet the futures of the invisible, the unheard voices—the teachers, firefighters, nurses, and the workers whose retirements we guard—on an engineered illusion while the host’s structural foundation is being drained.
For those of us who want to see the truth, interrogating Invariant Telemetry breaks the GPs’ hold on the one-way mirror of sovereignty, moving LPs from passive “Price Takers” to Sovereign Arbitrators of Value.
My sincere thanks to the experts mentioned above; your forensic work provided the clinical breadcrumbs that allowed an outside diagnostician’s thinking to validate the structural key to finally close the “invisible” void.
The question I invite the reader to consider is whether the logic holds: LPs cannot truly satisfy their fiduciary mandate while the primary instrument of measurement remains authored and controlled by the party being measured.
The logic of the Briefing Paper is provided below for your audit. To see what is currently invisible, we simply need an autonomous internal ruler.
Beyond the Streetlight Effect: An Alternative Path to LP Autonomy in Continuation Vehicles
With 80% of LPs cashing out of Continuation Vehicles (CVs), the industry is demanding more GP transparency. However, asking for better spreadsheets is merely the “Streetlight Effect”. Discover how LPs can achieve true investment autonomy by bypassing GP narratives and deploying independent operational telemetry—an Organisational CT Scan—to measure invariant asset health.
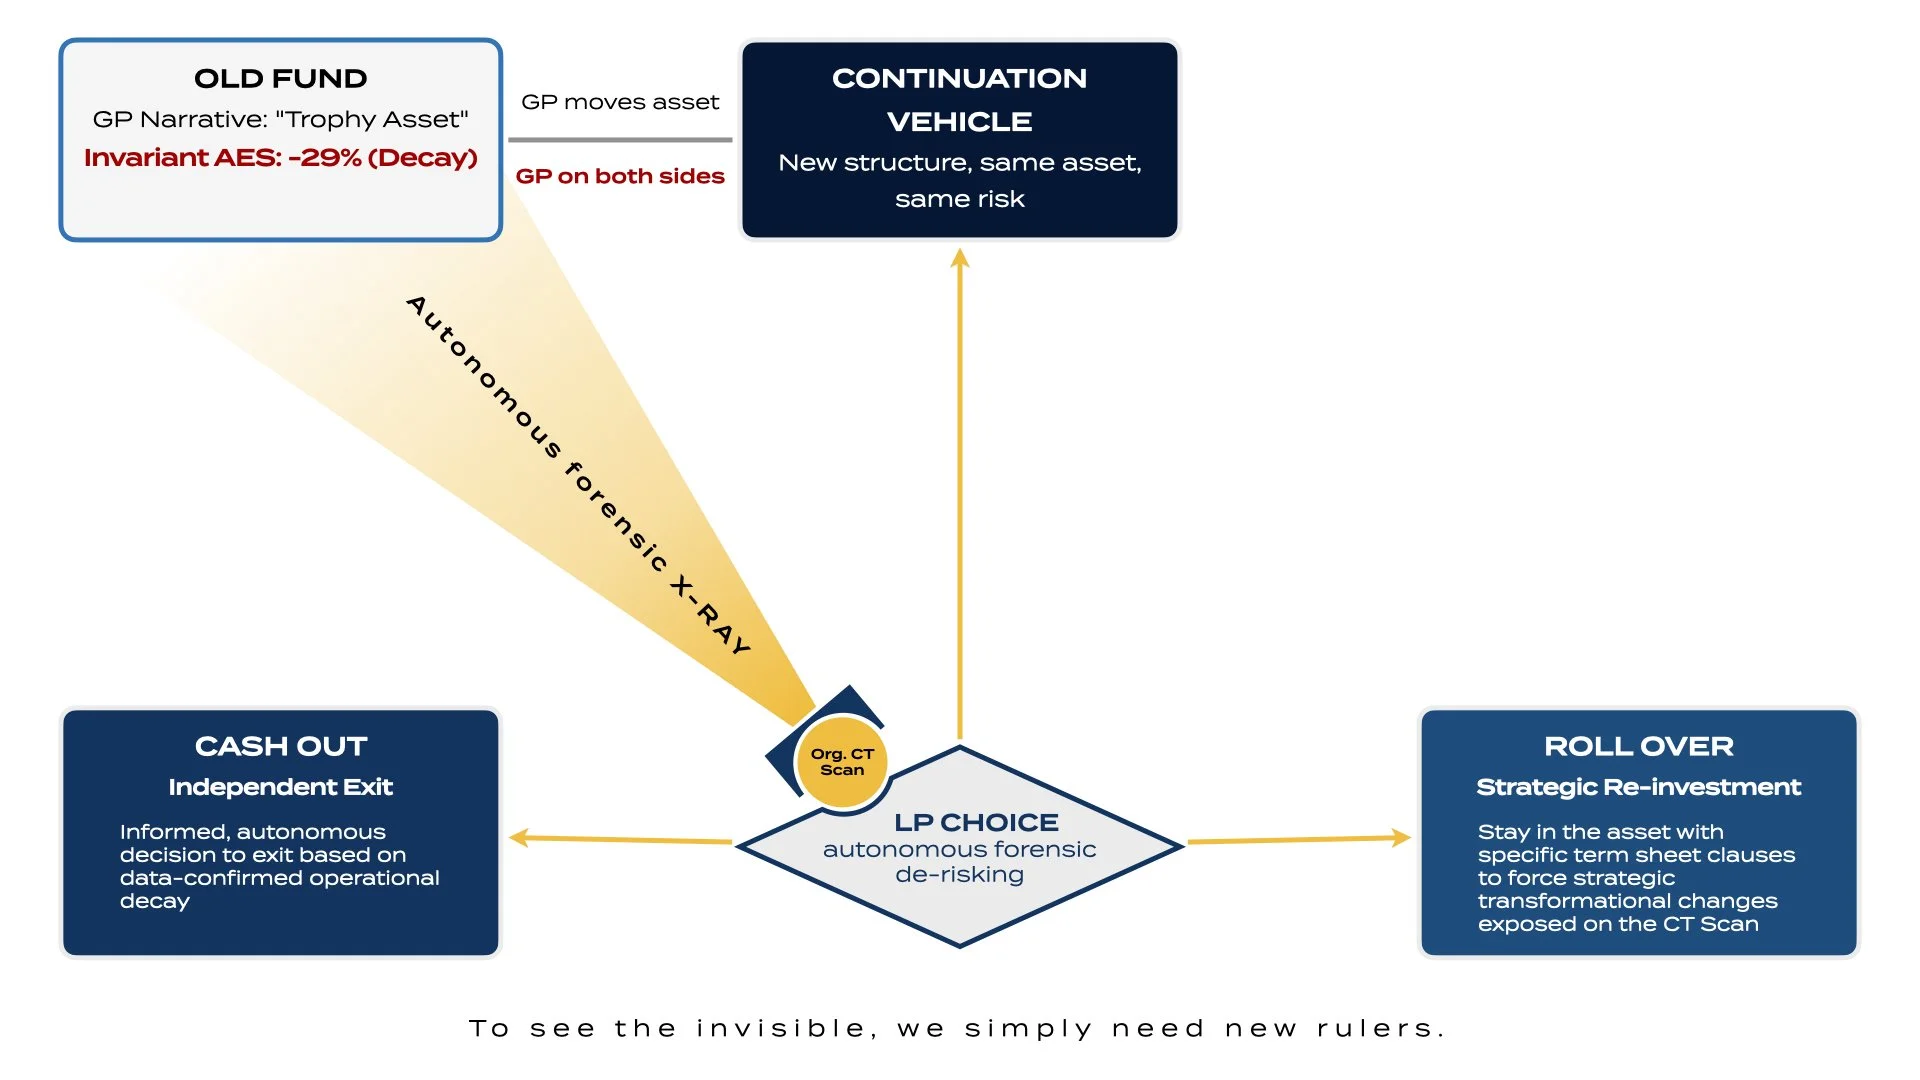
Professor Claudia Zeisberger raises the Private Equity cycle's defining question: when a GP moves a trophy asset into a Continuation Vehicle (CV), “Do LPs actually understand what they're being offered to roll into?”
As a lead diagnostician, my answer is no—but the “why” offers a fascinating opportunity.
This uncertainty drives severe market friction. Alexandra Heal’s Financial Times report “Private equity investor body sounds alarm on ‘conflict vehicles’” highlights a structural symptom: 80% of LPs cash out of CVs, increasingly viewing them as “conflict vehicles”. Consequently, ILPA is rallying General Partners (GPs) for more “transparency”.
I view this challenge differently. Demanding transparency within the current system mirrors the “Streetlight Effect”—searching for the lost keys under a lamppost simply because that is where the light is.
Here, financial models and GP-authored memos are the lamppost. Limited Partners (LPs) ask GPs to turn up the brightness (transparency). Yet, if an asset’s root-cause contagions lie outside that illuminated circle, brighter engineered metrics will not locate the missing keys.
To see the invisible opportunity, we must assess asset health exactly as a cardiologist examines a patient:
The patient “looks” fine (the GP’s “Trophy Asset” narrative).
The doctor prescribes standard treatment (conventional CV pricing and memos).
The scan exposes undeniable arterial plaque as a percentage, confidently providing a risk assessment (hidden structural decay).
A CAC scan bypasses surface symptoms to measure physical reality. If an asset hides a 29% structural decay beneath its financial façade, asking GPs for better spreadsheets will not uncover it.
A suggestion perhaps is move beyond prescribed guidelines hoping for GP collaboration, and instead explore autonomous PE “CAC Scores”.
LPs could hold such a key today. By running an CAC scan equivalent—using external shadow data to trace operational telemetry—LPs tangibly could calculate invariant health without demanding transparency or GP permission.
Shifting to such autonomy, would open an alternative path for LPs in Continuation Vehicles, without conflict. Independent telemetry evolves LPs into autonomous decision-makers.
To see the impossible, we simply bring a new ruler.